0242-2002-555
 contact@scsglobalaudit.vn

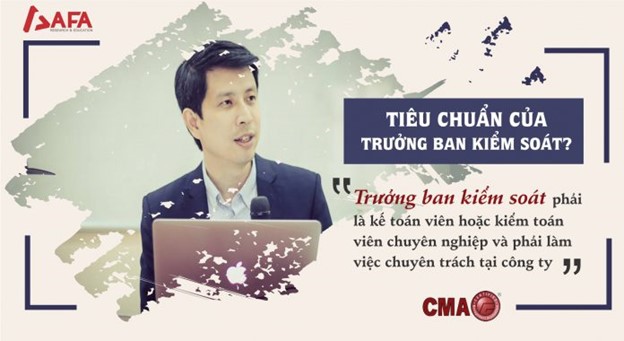
“The head of the supervisory board must be a professional accountant or auditor and must work full-time at the company.” Article 163 of the 2014 Enterprise Law stipulates the standards for the head of the supervisory board of a joint-stock company. This regulation has caused much debate over the past time. We discussed this issue with Mr. Phan Lê Thành Long, Director of the Certified Management Accountant Institute (CMA Australia) in Vietnam.
In your opinion, is it reasonable for the head of the supervisory board of a joint-stock company to be a professional accountant or auditor under current conditions?
The regulation that the Chairman of the Supervisory Board of a joint-stock company must have professional knowledge in finance, auditing, accounting, or control is consistent with international practices for committees with supervisory functions in joint-stock companies, especially public joint-stock companies. However, the strict legal requirement that “the Chairman of the Supervisory Board must be a professional accountant or auditor” is unreasonable because the job requirements of the Chairman of the Supervisory Board are different from those of an auditor or accountant.
So, how is a professional accountant or auditor defined?
In Vietnamese legal documents, there are no regulations or definitions of what constitutes a professional accountant or a professional auditor. Currently, the Ministry of Finance is the body organizing the national examination to issue the Practicing Auditor Certificate and the Accounting Service Practice Certificate. These two certificates aim to serve individuals who meet the conditions to register for independent auditing services and accounting service practice at auditing companies and accounting service providers.Thus, it does not mean that a person must have one of these two certificates to be considered a professional accountant or auditor. Because according to current regulations, these two certificates are to ensure that the provider of independent audit services and accounting services is authorized.
We can understand that an individual with a professional association membership certificate in accounting or auditing will be considered a professional accountant or auditor.
According to you, can the market currently meet all the requirements for the standard of the head of the supervisory board under the Enterprise Law?
In reality, the current number of joint-stock companies is so large that many companies have had to re-elect the head of the supervisory board for not meeting the standards as professional accountants or auditors. The number of people with professional association membership certificates in accounting and auditing cannot meet the demand. In addition, a large portion of those with professional association certificates are currently working at independent auditing firms. Thus, supply cannot meet demand.
What is your opinion on solutions to this problem?
The current head of the supervisory board of joint-stock companies should equip themselves with knowledge of accounting, auditing, and control, by participating in and becoming a member of professional associations in accounting and auditing both domestically and internationally. If they hold a professional membership certificate in accounting or auditing, they are considered a professional accountant or auditor.
Thank you.